
With mortgage rates still higher than many homeowners would like, refinancing is not worth considering for most people. The good news is that a new loan is not the only way to lower your monthly payment. You can shop your homeowners insurance, check your property tax assessment, ask your lender to recalculate your escrow, or ask about a mortgage recast.
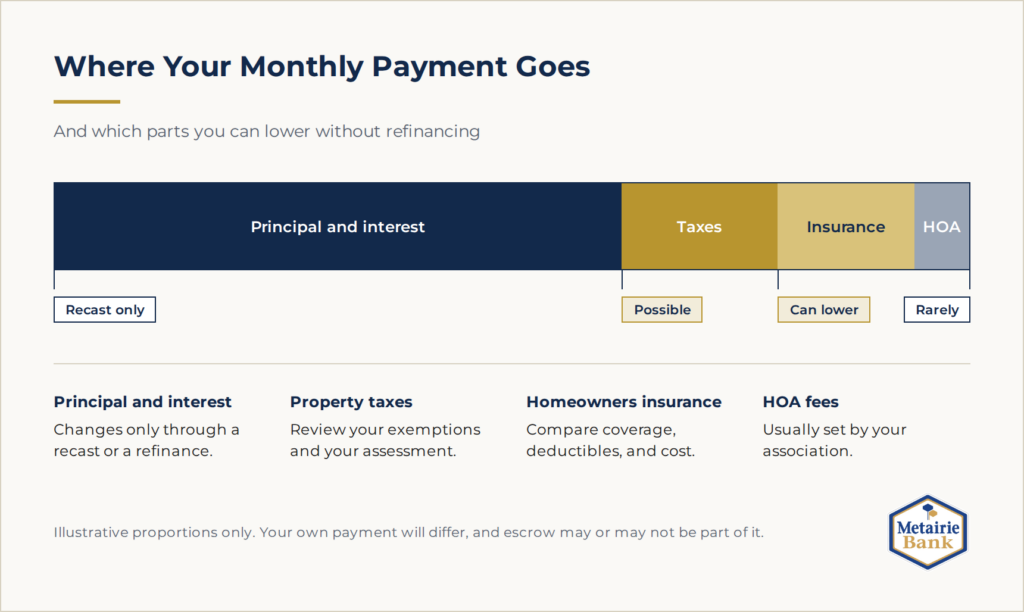
What Makes Up Your Monthly Mortgage Payment
Your monthly payment is more than the amount you borrowed and the interest on it. If your lender collects mortgage escrow, your payment also includes an amount to cover property taxes and homeowners’ insurance. The lender holds these funds in an escrow account and pays the bills when they are due. Only some parts of your payment can be lowered without refinancing, as shown below.
| Payment Component | Can You Lower It Without Refinancing? |
|---|---|
| Principal and interest | Only through a mortgage recast. Your interest rate and term stay the same unless you refinance. |
| Property taxes | Possibly, by confirming your exemptions and reviewing your property tax assessment. |
| Homeowners insurance | Yes, if you find comparable coverage at a lower cost. |
| HOA fees | Usually not. They may be added to your monthly payment, or you may pay them separately. |
Not every homeowner escrows. If your payment includes escrow, your statement will show a line for it. If you pay your property taxes and homeowners insurance directly instead, those bills are not part of your monthly mortgage payment, and the escrow tips in this article will not apply to you. The tips on insurance, property taxes, and recasting can still help you lower your overall housing costs.
Shop Your Homeowners Insurance
If you escrow, your lender pays your homeowners insurance premium from that account. Either way, you choose the provider and the amount of coverage. Your lender sets minimum coverage requirements, and flood insurance may be required for a federally backed mortgage on a home in a flood zone. For many homeowners in the Greater New Orleans area, flood coverage is a common consideration.
Every few years, compare coverage limits and deductibles as well as price. MB Insurance Agency offers home and flood coverage and can review your current policy. If you find comparable coverage at a lower cost, your escrow payment, and therefore your monthly mortgage payment, would drop. If you pay your premium directly, you would see the savings in your insurance bill instead.
Check Your Property Tax Assessment
Property taxes tend to increase, so it is worth reviewing your assessment. Louisiana law requires real estate to be reappraised at least once every four years, and residential property is generally assessed at 10 percent of fair market value.
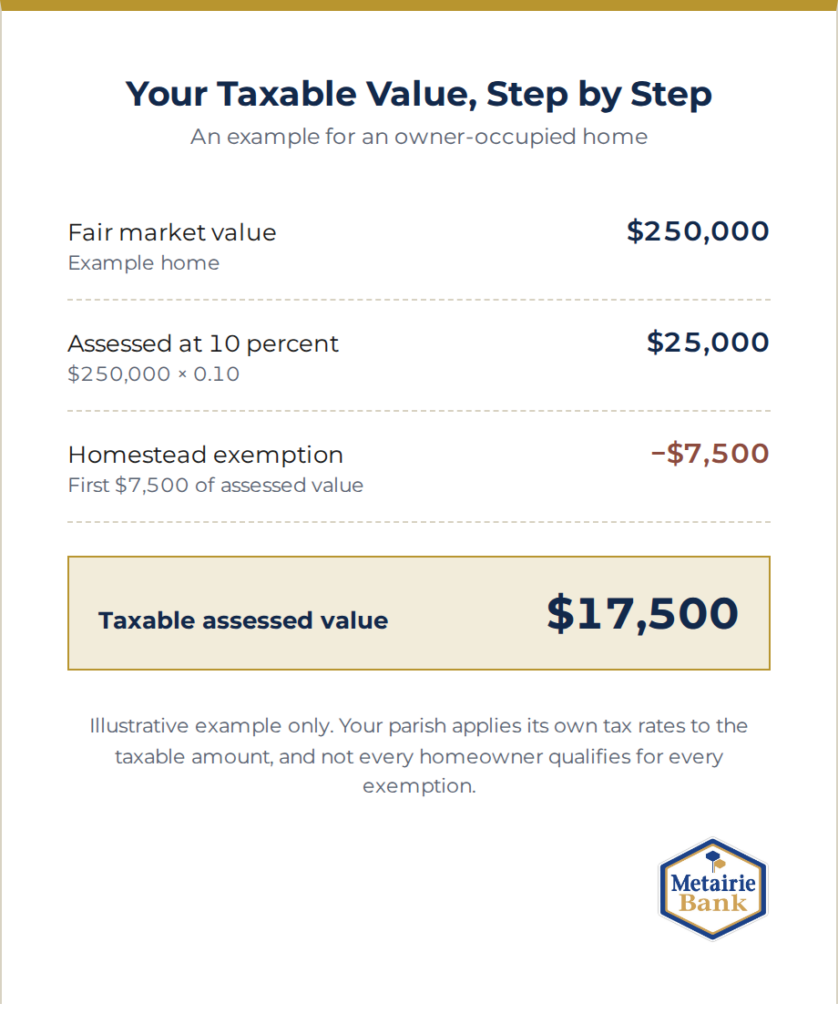
Confirm that you are receiving the homestead exemption, which exempts the first 7,500 dollars of assessed value on an owner-occupied home. Homeowners age 65 and older who meet the state income requirement may also qualify for a freeze on their assessed value. Homeowners in Jefferson Parish can find details at the Jefferson Parish Assessor’s Office. Homeowners in other parishes should contact their own parish assessor.
To consider an appeal, start by comparing the assessed values of similar properties on the assessor’s website with yours. Weigh the cost of an appeal against the likelihood of success, and consider speaking with a qualified appraiser or real estate attorney. A lower assessment would reduce your property taxes going forward. This article is general information and not tax advice.
Ask Your Lender to Recalculate Your Escrow
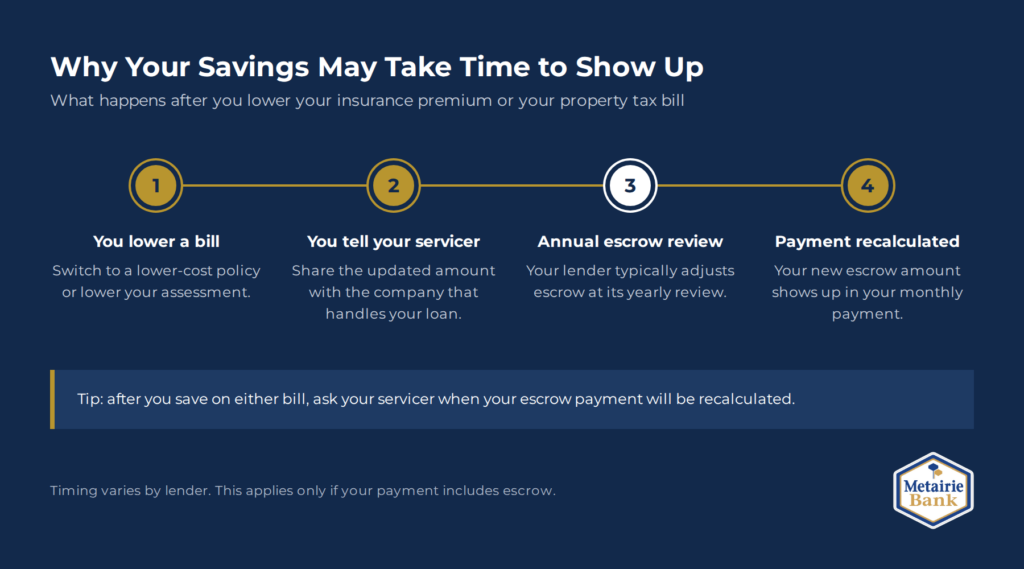
If your lender escrows your property taxes and insurance, a lower insurance premium or tax bill may not reduce your payment right away, because escrow payments are typically adjusted at your lender’s annual review. After you save on either bill, share the updated amount with your mortgage servicer and ask when your escrow payment will be recalculated.
Property taxes and homeowners insurance tend to rise over time, and so can your escrow payment. If rising taxes or premiums leave a shortage in your escrow account, you will have to make up the difference. Your lender sends an annual escrow statement with projections for the coming year, and the CFPB explanation of escrow accounts is a helpful reference.
Federal rules allow a servicer to hold a cushion of up to one-sixth of the estimated annual escrow disbursements. If the annual review shows a surplus of 50 dollars or more, the servicer must refund it within 30 days, provided your payments are current. A surplus under 50 dollars may be refunded or credited against next year’s escrow payments.
Consider a Mortgage Recast
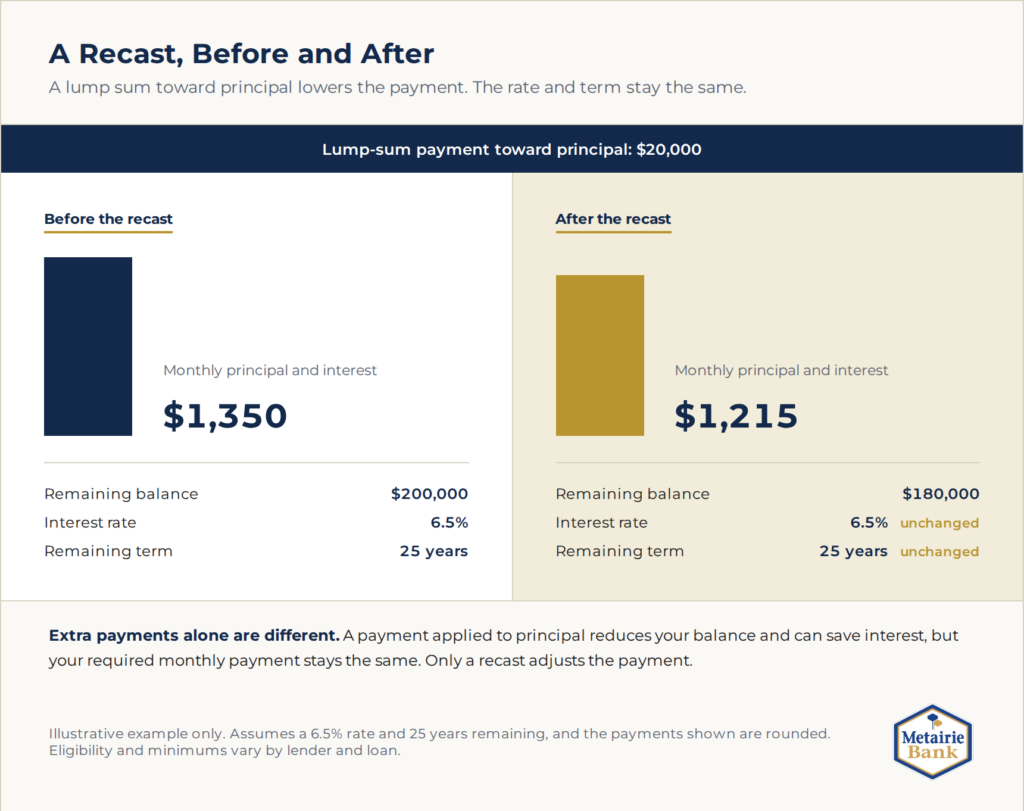
With a mortgage recast, you make a lump-sum payment toward your principal balance, and your lender readjusts your monthly payment over the remaining term of the loan. Metairie Bank offers recasting on its internal home mortgage loans, with a principal reduction of at least $10,000. Your interest rate does not change, and only the payment is adjusted. A lower balance can also reduce your total interest cost over time.
A recast is different from making extra payments. Extra payments can reduce your borrowing costs, depending on how the lender applies the money. If you make an additional payment, tell your lender to apply it to principal. Otherwise, the lender may treat it as an early regular payment. Applied to principal, extra payments help you pay off the loan faster and reduce total interest, but they do not lower your required monthly payment. Only a recast adjusts the payment.
Frequently Asked Questions (FAQs) About Mortgages
Does paying extra lower my monthly payment?
No. Extra payments can shorten the loan and reduce interest, but they do not lower the required monthly payment. Ask your lender to apply any extra payment to principal.
Why did my payment change?
Two common reasons are an adjustable-rate mortgage (ARM), whose interest rate can change after an initial fixed period, and escrow changes caused by rising property taxes or homeowners insurance premiums.
Is refinancing the same as a recast?
No. When you refinance, you apply for a new loan with a new rate and term, and you pay fees similar to those on your original mortgage. An appraisal may also be required. With a recast, your rate and term stay the same, and a lump-sum payment lowers your principal and your monthly payment.
Which loans are eligible for a recast?
Metairie Bank offers recasting on its internal loans. Mortgages backed by federal programs, including FHA, VA, and USDA loans, generally cannot be recast.
How much could I save with a recast?
Use the Mortgage Calculator to estimate your payment. Enter your remaining balance, remaining term, and interest rate, then repeat with the balance after your lump-sum payment and compare the two monthly payments.
Questions About Your Mortgage Payment?
If you have questions about lowering your monthly payment or about refinancing, talk to a Metairie Bank lender. Our mortgage lending team can help you weigh your options and decide whether refinancing makes sense for you.